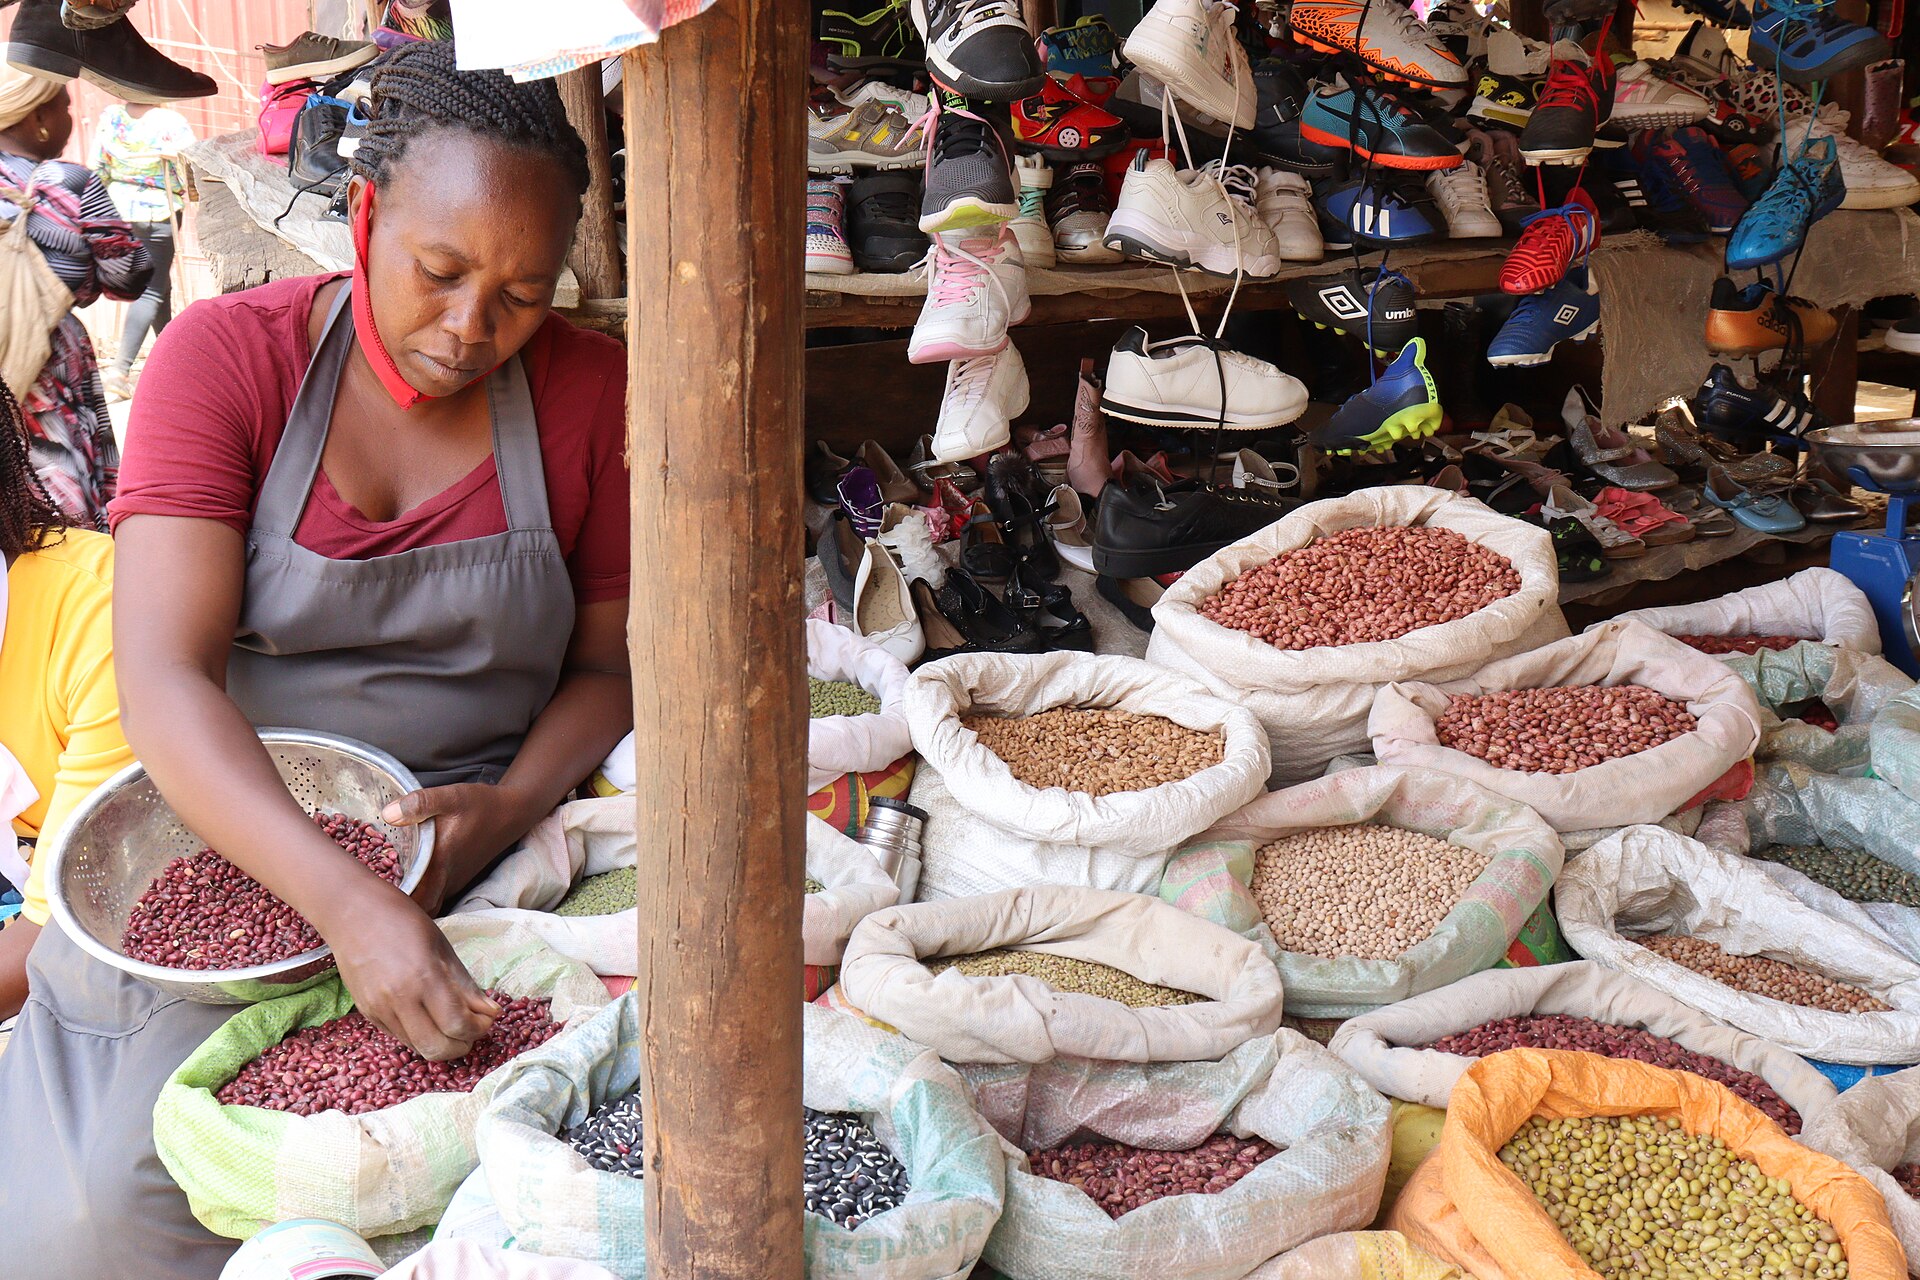
In a Lagos market, a tomato seller waves away cash and points to a hand-written phone number taped to her stall. Payment arrives in seconds, confirmed by a text message on a phone with a cracked screen. Scenes like this, repeated millions of times a day from Dakar to Dar es Salaam, describe the most consequential financial shift in Africa’s modern history: mobile money has grown from a Kenyan experiment into the primary bank account for a huge share of the continent’s adults.
Industry data from the GSMA, the mobile operators’ association, counts registered mobile money accounts in Africa in the high hundreds of millions, with transaction values running into the hundreds of billions of dollars a year. The model is elegantly simple: a network of human agents — kiosks, shops, petrol stations — converts cash to electronic value and back, while the ledger lives on the phone network rather than in a bank branch. For rural customers hours from the nearest bank, the agent on the corner is the bank.
From Transfers to a Full Financial Life
The first generation of services did one thing — person-to-person transfers — and did it well enough to transform remittances. The current generation is broader: savings pockets that pay interest, micro-loans scored by phone-usage data, insurance premiums collected in tiny daily amounts, merchant payments, school fees, government transfers and cross-border corridors that undercut traditional money transmitters. Nigeria’s agent banking networks and the rapid licensing of payment service banks show the model still expanding into its largest market. Development economists tracking the change, including teams at the World Bank, link mobile money access to measurable drops in poverty, partly because households can receive help quickly in a crisis.
None of this is frictionless. Agent liquidity — the float of cash and e-money a kiosk holds — fails customers at busy moments; fraud through social engineering is a persistent problem; and regulators must balance consumer protection against the innovation that made the system work. Interoperability between rival networks, long resisted, is improving under regulatory pressure, and central banks are layering instant-payment switches over the top. Follow the business story in our business coverage.
The Next Contest: Credit and Cross-Border
The Agent on the Corner
Behind every mobile-money statistic stands a person with a kiosk, a float of cash and a phone: the agent. Networks now employ millions of agents across Africa, and their economics — commissions, liquidity management, the daily risk of holding cash — are the system’s least glamorous and most decisive layer. An agent who cannot honour a withdrawal because the float ran dry does more damage to trust than a month of advertising can repair, which is why operators invest in agent credit scoring, float loans and dense placement as fiercely as in apps. The occupation has also become a first rung on the economic ladder in places with few rungs, particularly for women and young people. Financial inclusion is usually photographed as a smiling customer with a phone. Its working machinery is an agent, under an umbrella, making change — and the milestone numbers ultimately count how many of those umbrellas a continent has raised.
The frontier now is credit and borders. Phone-scored lending reaches borrowers with no formal history, but opaque pricing and aggressive collection have drawn regulatory attention. Cross-border mobile remittances, meanwhile, attack one of the world’s most expensive corridors — sending money within Africa can cost several times the global average. Whoever solves trust, pricing and compliance at once will own a large piece of the continent’s financial future. The tomato seller, phone in hand, is unlikely to go back to cash either way.